
Small Business Loans for Woodland, CA Sit-down Restaurants, Home Builders and Physician Offices
For a Woodland, CA business, small business loans come here in four shapes (working capital, term, revolving line, inventory) beside equipment financing and the merchant cash advance, which is not a loan.
- Six funding types compared
- Phone or a short online form
A distributor, restaurant, home builder or physician office can call (530) 324-0236 or send one short form, and funding partners review it and make their own offers.
Industry funding notes for Yolo County, CA
Pages for trades with county business figures, and short notes for the rest.
 Restaurants
 Medical practices
 Dental offices
 Salons and barber shops
 Gyms and fitness studios
Show all: Retail stores, Construction, Auto repair shops, Child care, Landscaping, Hotels and motels, Manufacturing, Real estate agents and Cafes and coffee shops.
How a request moves from first contact to a decision
A call or the form, a conversation, then a partner review.
Reach out
Call, or send contact details and three ranges.
Talk it through
What the money is for, and which product fits it.
Partner review
A funding partner checks the business and asks for records.
Decide
Compare any offer on total cost before signing.
Where each product fits a Woodland, CA business
6 products, each with its own page: what it pays for and how it works.
Working capital loans
Money for payroll, rent and supplier bills while customer invoices are still open.
Business term loans
One lump sum with a fixed schedule, used for a business purchase, equipment packages or a second location.
Business lines of credit
A revolving limit to draw on for supplier bills and pay back as invoices clear.
Inventory financing
Funding tied to stock: pallets, parts and supplies bought ahead of a large order.
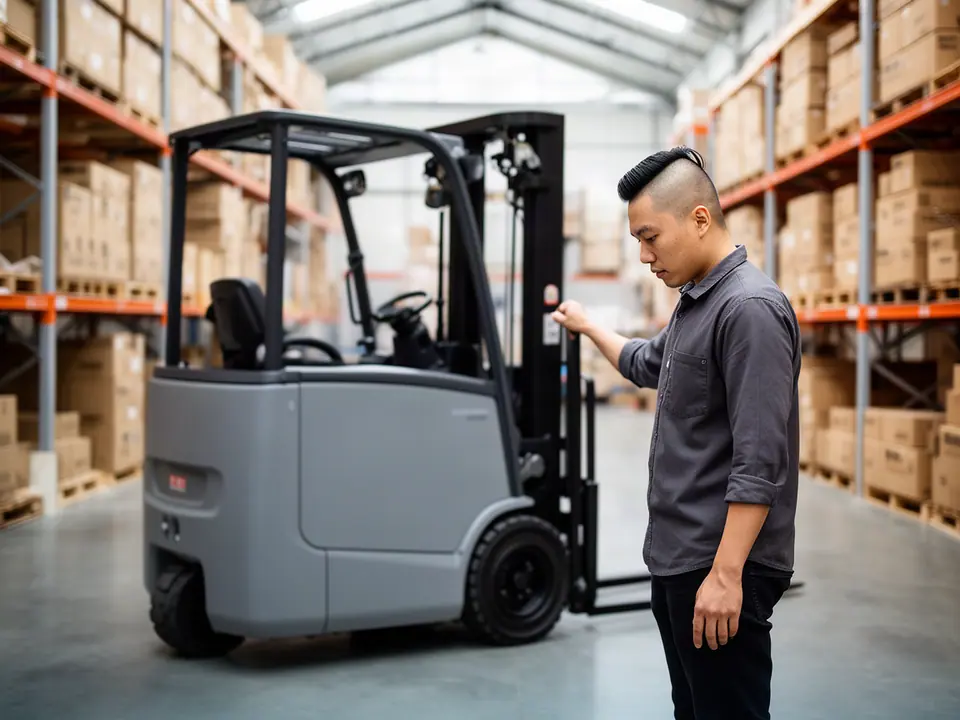
Equipment financing
Loans and leases for forklifts, kitchen lines and shop machines, with ownership and security defined by the provider’s agreement.
Merchant cash advances
A purchase of future card sales, collected from eligible receipts under the agreement.
Line of credit vs term loan for Woodland, CA wholesale distributors
Term loan money arrives in a single payout, and the schedule to retire it is set in advance. With a line of credit, the business borrows against a set limit, repays, and can borrow again up to that limit. For a distributor, the bill itself points to the answer: a one-time cost with a known price, such as buying out a retiring partner, sits well with a term loan, while a gap that opens and closes every month, such as paying a supplier before a retail customer settles its invoice, sits well with a line.
| Point | Term loan | Line of credit |
|---|---|---|
| How the money arrives | One lump sum at closing | Draws up to the limit, when needed |
| Interest is charged on | The full balance from day one | Only the amount drawn |
| Payment pattern | The same amount each month | Rises and falls with the balance |
| Good match | A purchase with a known price | Bills that recur with invoice timing |
Payroll is where a distributor's timing gap shows first. The 294 wholesale trade establishments in Yolo County, CA paid $682.8 million in wages in 2023, the largest payroll of any sector in the county's County Business Patterns table, and each payday fell due whether or not customer invoices had cleared.
Equipment financing or leasing for a Yolo County, CA distributor?
With equipment financing, the business owns the forklift or pallet jack from the start, the payments cover the price plus interest, and the machine itself is the collateral. With a lease, the provider keeps ownership; at the end of the term the business returns the unit, renews, or buys it at fair market value or for a $1 buyout, depending on the lease type.
Which one costs less depends on the offer in hand, so compare the full numbers rather than the monthly figure alone:
- The total of all payments, plus any buyout at the end
- Who pays for maintenance, insurance and repairs during the term
- What happens if the business needs a larger unit halfway through
- Whether the payment is fixed or can change with a rate index
- Any fee for ending the agreement early
What banks look for in a business plan from a Woodland, CA distributor
A business plan that holds up in a bank review answers a few plain questions in writing. A lender reading it wants to see where repayment comes from, not a mission statement:
- What the money buys, with quotes or invoices attached
- Which customers and contracts produce the revenue that repays it
- Two or three years of financial statements, plus the current year to date
- Who runs the business and how long they have run it
- What collateral backs the request, if any
A request sent through this site does not start with a full plan. The first call covers the amount, the use and the timing, and a funding partner can ask for a plan or projections if its own review needs them.
Business loans in California for Yolo County, CA wholesale distributors
A five-person operation is ordinary in this county. Just over half of Yolo County, CA's employer establishments sat in the smallest size class in 2023: 2,286 of 4,509 had fewer than five employees, or 50.7% (County Business Patterns; share by our arithmetic).
| Employees | Establishments | Share |
|---|---|---|
| Fewer than 5 | 2,286 | 50.7% |
| 5 to 19 | 1,467 | 32.5% |
| 20 or more | 756 | 16.8% |
| All sizes | 4,509 | 100.0% |
Nonemployer Statistics, a separate Census program, counted 14,975 businesses with no paid employees in Yolo County, CA in 2024, including 195 in wholesale trade.
Closer to the office, the ZIP Code Business Patterns file for 2023 put 775 employer establishments at a ZIP Code 95695 address, and 55.2% of those had fewer than five employees. A request can come by phone or the form from anywhere in Yolo County, CA. The Woodland, CA business loans page explains why ZIP 95695 reaches well past the city, and the nearby places page covers the communities around it. Builders, physician offices and auto repair shops each get their product matches on the industries page; a distributor's 13-week cash forecast, worked week by week, starts the blog.
How business loans work for Woodland, CA home builders and physician offices
- Dial (530) 324-0236, or open the request form on the apply page (contact details and three ranges).
- On the call, name what the money pays for, the amount and the date it is needed.
- Funding partners with a product for that use receive the request.
- A partner reviews bank statements, tax returns and the purchase details, and may check credit as part of that review.
- Any offer states the amount, rate or factor, term and payment; the business can accept it or walk away.
For housing, the Census Building Permits Survey logged permits for 397 new privately owned units across Yolo County, CA in 2025. A builder working on one of those homes can use this site for equipment or working capital between draws; the construction loan and the land stay with a real estate lender.
Small headcounts show up in medicine as well; County Business Patterns placed 60 of Yolo County, CA's 87 offices of physicians in the under-five-employee class for 2023 (NAICS 6211). Exam-room equipment, a payroll gap while insurance claims are paid, and the furnishings for another office each match a different product.
Types of business loans Woodland, CA wholesale distributors use
- Working capital loans: wages, rent and vendor bills during an invoice wait
- Business term loans: a fixed schedule for a business purchase or a large one-time cost
- Business lines of credit: a revolving limit for bills that recur
- Inventory financing: goods purchased before a big order ships
- Equipment financing: forklifts, kitchen lines and shop machines
- Merchant cash advances: card receipts sold ahead of time, which is not a loan
The loan types page sets them side by side, and the step-by-step page lists the documents a partner review can call for.
Deposit and payment questions on Woodland, CA loans
How much deposit do you need for a business loan?
There is no single figure: a deposit, or down payment, is a term each funding partner sets for the deal in front of it. It comes up with equipment financing and business purchases, where the item or business being bought secures the debt. A working capital loan or credit line can rest more on revenue and bank statements. Ask each offer what cash it needs at signing, then weigh that against the payment.
What is the monthly payment on a $50,000 business loan?
Rate and term decide it. Illustration only, invented figures: take $50,000, an annual rate of 11% and five years; the 60 installments land at $1,087.12 each, $65,227.20 altogether. The same amount over 36 months is $1,636.94 a month and $58,929.84 in total, so the shorter term costs $6,297.36 less in interest. A real offer can differ on both.
Does sending the form commit a Woodland, CA business to anything?
No. Sending the opening form begins an inquiry, not an application for credit. Any offer that follows comes from a funding partner, which may check credit during its own review, and the business decides whether to accept it, ask for changes or decline.
Woodland, CA owners: name the purchase, then call or apply
Call (530) 324-0236 to talk through the amount and what it pays for, or send the short form with contact details and three ranges.
Send the short request in Woodland, CA
Contact details plus three ranges: time in business, annual revenue and the amount sought. A conversation about the need comes next, then funding partners review.
- Six funding types compared
- Phone or a short online form
- Yolo County, CA
See our Privacy Policy, Terms and SMS Terms.
Other funding pages for this purchase
About us
About Timbershore Lending Group in Woodland, CA: how a business funding request reaches funding partners, and where a distributor can apply.
How to reach a person
Contact Timbershore Lending Group in Woodland, CA at (530) 324-0236, with the questions to ask before and during a business loan request.